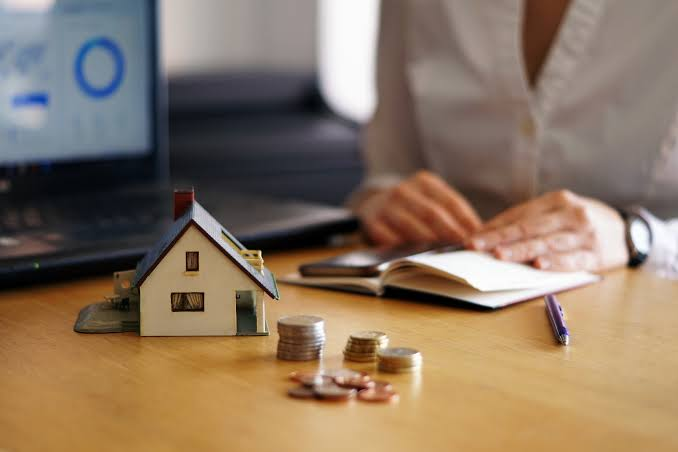
A Perth home loan broker will be familiar with the many lenders, can help you with all the requirements with the government’s 5 % deposit scheme (Perth price cap $850,000) and the $10,000 WA first home owner grant scheme for new homes, and take care of the loan application, from pre-approval to settlement. In most cases, the broker gets his commission from the lender, and so it’s not required for you to pay them anything.
- 01. So, what is the role of a home loan broker?
- 02. First Home Buyer Support in Perth (2026)
- 03. Step-by-Step: Buying Your First Home With a Broker
- 04. Bank vs Home Loan Broker: Which Is Better for First Home Buyers?
- 05. How to Choose the Best Home Loan Broker in Perth
- 06. Tips to Strengthen Your Loan Application
- 07. A Perth Broker With Tax Expertise
- 08. Frequently Asked Questions
- 09. Do Perth home loan brokers charge a fee?
- 10. Is it possible to purchase a house with 5% deposit in Perth?
- 11. Does WA have First Home Owner Grant for existing homes?
- 12. What is the length of the pre-approval process?
- 13. Final Thoughts
- What Are Guest Post Guidelines? A Beginner’s Guide
- Link Exchange in SEO: A Complete Guide to Know
- The Art of the Hook: How to Write Enticing Introductions in Blogging and Essay Writing
- How a Website Audit Helps Improve User Experience and SEO Together
- What SEO Content Tips Top Digital Marketing Firms Always Follow
- How to Rank Your Blog in Google’s Top 10 Search Results

Buying a home is a big commitment.This is a big purchase and this is surely their first property in Perth. We have seen prices to increase significantly. The median house price in Perth rose by 18.7% in a year to $980,000 in the June 2026 quarter (REIWA). The RBA cash rate is also trending upwards, rising to 4.60% in September 2026.
The stakes are high, and a good broker can help ease the stress of the home-buying process. This guide will be helpful in understanding this.
So, what is the role of a home loan broker?
The home loan broker is a licensed credit professional between you and the lenders. They:
- Evaluate your income, expenses, deposit and goals.
- Shop around for home loans at numerous banks and non-bank financial institutions.
- Describe what government schemes you might be entitled to.
- Provide you with pre-approval to make offers with confidence.
- Write, and submit, your loan application.
- Oversee settlement process.
Mortgage brokers make recommendations for Australian loans according to the principle of putting the borrower’s interests first (ASIC Moneysmart).
First Home Buyer Support in Perth (2026)
| Scheme | What it offers | Key rule for Perth |
|---|---|---|
| 5% Deposit Scheme (federal) | Buy with a 5% deposit and no lenders mortgage insurance (LMI) | Property price cap of $850,000 in Perth; no income caps since 1 October 2025 |
| WA First Home Owner Grant | $10,000 grant | Brand new homes only, capped at $800,000 in Perth and the south of WA |
| WA transfer duty concessions | Reduced or no stamp duty for eligible first home buyers | Thresholds change, so check RevenueWA for current limits |
Your broker will check which of these you qualify for and how to combine them.
Step-by-Step: Buying Your First Home With a Broker
- Free first meeting. Your broker looks at your income, savings, debts and goals.
- Borrowing power check. You find out how much you can realistically borrow, including a buffer for higher rates.
- Scheme check. Your broker confirms if you can use the 5% Deposit Scheme, the FHOG or duty concessions.
- Loan comparison. They shortlist suitable loans and explain the differences.
- Pre-approval. You get conditional approval so you can shop with confidence.
- Find your home. Make an offer within your budget.
- Formal approval. Your broker manages the lender’s valuation and paperwork.
- Settlement. You get the keys.
Bank vs Home Loan Broker: Which Is Better for First Home Buyers?
| Factor | Going direct to a bank | Using a home loan broker |
|---|---|---|
| Loan choice | One lender’s products | Many lenders’ products |
| Advice on schemes | Limited to that bank’s participation | Broad guidance across schemes |
| Legal duty | Bank staff sell their own products | Broker must act in your best interests |
| Paperwork help | You do most of it | Broker manages the process |
| Cost to you | Usually none | Usually none (lender pays commission) |
Australians have embraced brokers. Mortgage brokers facilitated a record 81.6% of all new home loans in the June 2026 quarter, according to research commissioned by the MFAA (MFAA).
How to Choose the Best Home Loan Broker in Perth
When searching for the best home loan broker in Perth, look for:
- Licensing: they hold an Australian Credit Licence or are an authorised credit representative.
- Panel size: access to a wide range of lenders.
- First home buyer experience: they know the schemes inside out.
- Clear disclosure: they explain how they are paid.
- Great reviews: look for detailed Google reviews from real buyers.
- Tax knowledge: a broker who understands tax can help you plan for the long term.
Tips to Strengthen Your Loan Application
- Pay down credit card limits, not just balances. Lenders look at limits.
- Avoid new debts, like car loans or buy now, pay later, before applying.
- Show steady savings over at least three months.
- Keep your employment stable during the process.
- Have your tax returns and payslips ready.
A Perth Broker With Tax Expertise
TFP Tax Accountants offers something unusual: licensed mortgage broking from a team that also handles tax. Director Kamal Sharma is both a Registered Tax Agent and a Licensed Mortgage Broker, so your home loan and tax position are looked at together.
The team helps first home buyers with home loans in Perth, scheme checks and pre-approvals. You can read client feedback on their Google Business Profile.
Frequently Asked Questions
Do Perth home loan brokers charge a fee?
Most brokers will not charge you any fees, as they are given a commission by the lender. Your broker is obligated to inform you how he or she gets paid.
Is it possible to purchase a house with 5% deposit in Perth?
Yes, provided the property is not worth more than $850,000 in Perth and the 5% Deposit Scheme is available. Your broker will be able to verify eligibility.
Does WA have First Home Owner Grant for existing homes?
No. New homes or homes that have been significantly upgraded are eligible for this WA First Home Owner Grant, amounting to $10,000, within price capped homes.
What is the length of the pre-approval process?
It may take anywhere from a few days to couple of weeks, which all depends on the lender and how quickly they get your documents.
Final Thoughts
A trusted home loan broker in Perth will help you use all the home loan schemes and make sure you are directed to a suitable loan in the market where interest rates are on the rise. Exercise caution weeding and begin early, get pre-approved, and select a broker who is familiar with both lending and tax.
This is a general article and not a credit advice. It does not take into account your goals, financial situation or needs. Before you make your decision, consult a licensed mortgage broker. The rules of the Scheme and figures are current to the date of October 2026 and subject to change.

Facebook Discussion